Mes del terror en Buscalibre 5% dto  Ver más

Enviar a
Provincia de Madrid
0
  • argentina
  • chile
  • colombia
  • españa
  • méxico
  • perú
  • estados unidos
  • internacional

Selecciona tu país

América

Europa

Resto del mundo

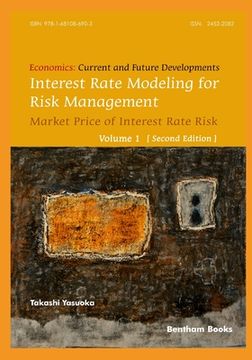
portada Interest Rate Modeling for Risk Management: Market Price of Interest Rate Risk (Second Edition) (en Inglés)
Formato
Libro Físico
Idioma
Inglés
N° páginas
324
Encuadernación
Tapa Blanda
Dimensiones
25.4x17.8x2.1 cm
Peso
0.78 kg.
ISBN13
9781681086903
Categorías

Interest Rate Modeling for Risk Management: Market Price of Interest Rate Risk (Second Edition) (en Inglés)

Takashi Yasuoka (Autor) · Bentham Science Publishers · Tapa Blanda

Interest Rate Modeling for Risk Management: Market Price of Interest Rate Risk (Second Edition) (en Inglés) - Yasuoka, Takashi

Libro Nuevo Importado
Envío: 11 a 15 días háb.
145,14 €130,63 €
-10%
Libro Nuevo

Quedan más de 100 unidades

130,63 €
Llega entre el 13 Nov y el 23 Nov a Provincia de Madrid. Seleccionar ubicación

Reseña del libro "Interest Rate Modeling for Risk Management: Market Price of Interest Rate Risk (Second Edition) (en Inglés)"

Interest Rate Modeling for Risk Management presents an economic model which can be used to compare interest rate and perform market risk assessment analyses. The key interest rate model applied in this book is specified under real-world measures, and the result is used as to generate scenarios for interest rates. The book introduces a theoretical framework that allows estimating the market price of interest rate risk. For this, the book starts with a brief explanation of stochastic analysis, and introduces interest rate models such as Heath-Jarrow-Morton, Hull-White and LIBOR models. The real-world model is then introduced in subsequent chapters. Additionally, the book also explains some properties of the real-world model, along with the negative price tendency of the market price for risk and a positive market price of risk (with practical examples). Readers will also find a handy appendix with proofs to complement the numerical methods explained in the book. This book is intended as a primer for practitioners in financial institutions involved in interest rate risk management. It also presents a new perspective for researchers and graduates in econometrics and finance on the study of interest rate models. The second edition features an expanded commentary on real world models as well as additional numerical examples for the benefit of readers.

Opiniones del libro

Preguntas frecuentes sobre el libro

Todos los libros de nuestro catálogo son Originales.
El libro está escrito en Inglés.
La encuadernación de esta edición es Tapa Blanda.

Preguntas y respuestas sobre el libro

¿Tienes una pregunta sobre el libro? Inicia sesión para poder agregar tu propia pregunta.

Opiniones sobre Buscalibre

Ver más opiniones de clientes